

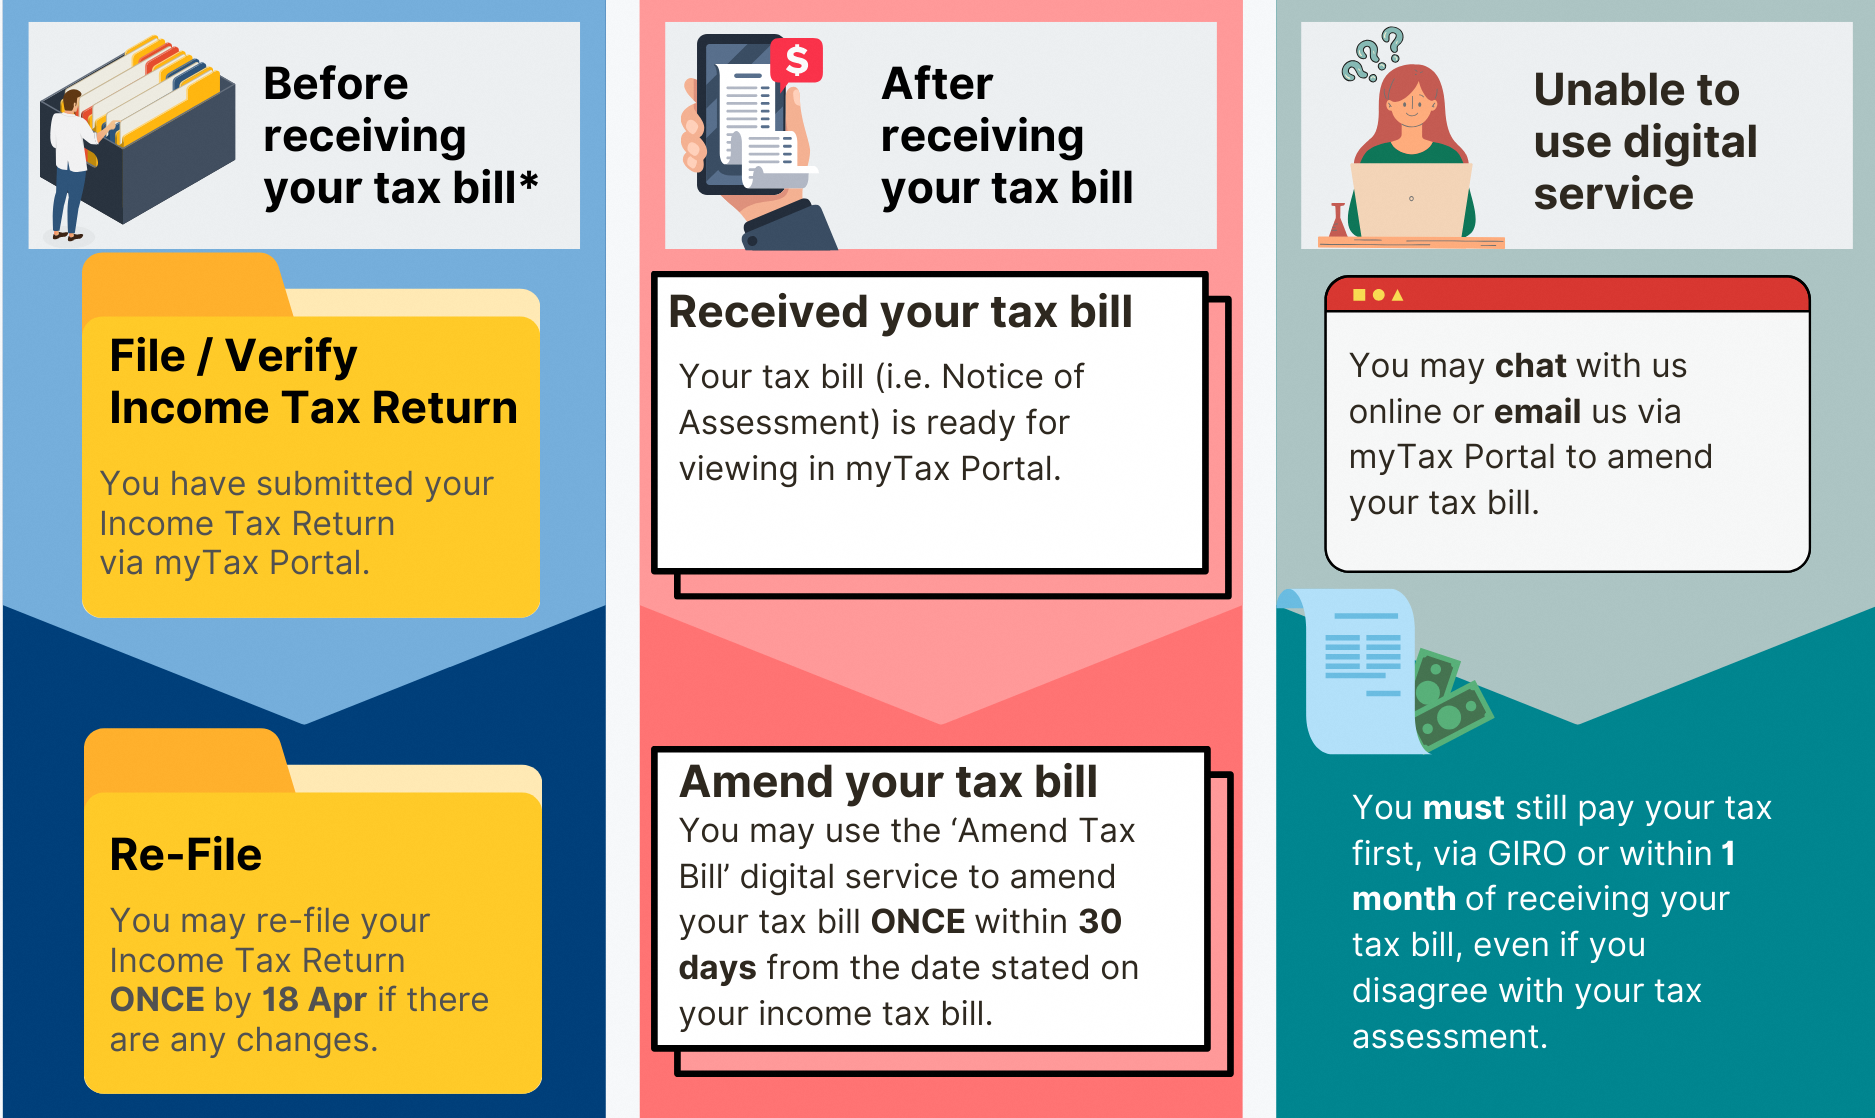
You may re-file your Income Tax Return once by 18 Apr. Otherwise, you may amend your tax bill using ' Amend Tax Bill' digital service on myTax Portal within 30 days.
*If you are under the Direct Notice of Assessment (D-NOA) scheme, this is not applicable to you. Refer to Tax Season 2026 - All you need to know for more information on D-NOA.
Incorrect or unsupported employment expense claims
Employment expenses are expenses that are 'wholly and exclusively' incurred in the production of your employment income in Singapore.
Examples of non-allowable employment expenses include:
- Personal meals, housing rent, subscription fees, and phone or internet bills;
- Public transport expenses for travel between home and the workplace;
- Private car expenses (i.e. for cars with licence plates starting with “S”), even if the car is used for work purposes; and
- Purchases of electronic devices, such as mobile phones and computers, for work purposes.
Taxpayers should retain relevant supporting documents, such as receipts and invoices, to substantiate your claims and produce them when requested by IRAS. Claims based on estimates are not acceptable.
If your employment expense claims are incorrect or not supported by proper records, you are required to adjust or withdraw your claims through the following channels:
- To adjust or withdraw your claims: Use the 'Amend Tax Bill' digital service on myTax Portal.
- To withdraw all your claims: Submit the 'Withdraw Employment Expense Claims' FormSG.
- If you need to adjust your claims but are unable to use the ‘Amend Tax Bill’ digital service: Chat with us for assistance
You are responsible for ensuring that your tax declarations are accurate. False, incorrect, and unsupported claims may result in additional tax and penalties of up to three times the tax undercharged. Individuals charged in court may also face a fine of up to $10,000 , imprisonment of up to three years, or both.
Obligation to pay taxes
If you are not paying your taxes via GIRO, a late payment penalty will be imposed for taxes that are outstanding after 1 month. For details, please refer to Penalties for Late or Non-Payment.
We will refund you the credit balance, if any, within 30 days from the date of your new tax bill [i.e. Notice of Assessment (Amended)] if we revise your assessment after reviewing your objection. For details, please refer to Tax Refunds.
Before receiving your tax bill
If you have filed your Income Tax Return online on myTax Portal, you may re-file once by 18 Apr.
Steps to re-file your Income Tax Return:
- Log in to myTax Portal.
- Select "Individuals" > "File Income Tax Return".
- Follow the instructions shown on the screen to re-file.
When you re-file, you must include all your income details, expenses, donations and relief claims, where applicable.
Once you have re-filed successfully, your new submission will override the previous submission.
After receiving your tax bill
Deadline for filing amendments
Your amendments must be filed within 30 days from the date stated in your income tax bill (i.e. Notice of Assessment). IRAS will review your amendments and inform you of the outcome. You may refer to our FAQ (PDF, 286 KB) for more information.
How to file amendments
You may file an amendment using the 'Amend Tax Bill' digital service on myTax Portal for any of the following purposes:
- Revise income declaration;
- Add or amend claims for deductions and reliefs;
- Claim Parenthood Tax Rebate (PTR) (if the PTR account has not been created for your child); or
- Change in tax residency status (from non-resident to resident, if applicable).
Once your amendment has been processed, IRAS will issue your revised tax bill (digital/ paper) within 5 working days. For more complex cases, processing may take up to 2 months. We will notify you via your preferred notification mode when your revised tax bill is finalised or if more information is needed.
FAQs
For assessments raised in 2022 and subsequent years, you have up to 4 years from the end of that relevant year to inform us of your claims. For example, if the assessment was raised in 2022, you have up till 31 Dec 2026 (i.e. 2022 + 4 years) to inform us of your claim.
To claim for eligible reliefs in the preceding years, you may file an amendment using the 'Amend Tax Bill' digital service on myTax Portal.